North Carolina Wrongful Death Claims: Does a Minor's Age Extend the Two-Year Deadline?
Why a Minor's Age Does Not Extend North Carolina's Two-Year Wrongful Death Deadline
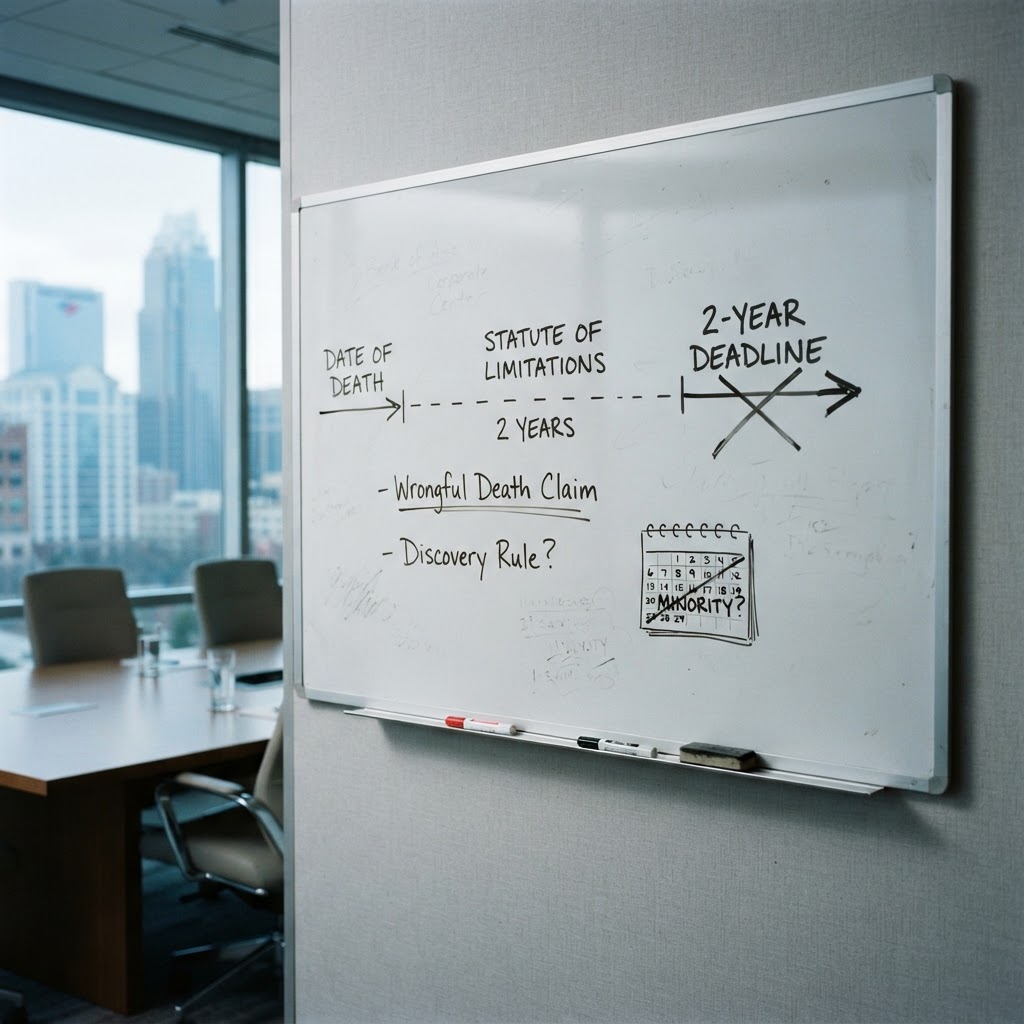
One issue that occasionally arises in catastrophic injury and wrongful death claims is whether North Carolina's two-year wrongful death statute of limitations is extended when the deceased was a minor. The answer, under current North Carolina law, is no.
The Two-Year Deadline Still Applies
North Carolina's wrongful death statute generally requires that a wrongful death action be filed within two years of the decedent's death. The cause of action accrues on the date of death, regardless of the decedent's age.
Minority Tolling Does Not Save the Claim
Some may assume that because North Carolina generally tolls statutes of limitation for minors, the same rule applies to wrongful death actions involving a deceased child or minor beneficiaries. However, the North Carolina Court of Appeals rejected that argument in Boomer v. Caraway, 116 N.C. App. 723, 449 S.E.2d 215 (1994). The court in Boomer held that North Carolina's minority tolling statute, N.C. Gen. Stat. § 1-17, does not extend the deadline because the wrongful death claim belongs to the personal representative of the estate, not to the minor beneficiaries themselves.
The court explained that when the statute of limitations expires as to the personal representative, it also expires as to the beneficiaries, even if those beneficiaries are minors.
Why This Matters for Insurance Carriers
When evaluating North Carolina wrongful death claims, claims examiners should focus on the date of death and determine whether a lawsuit was filed within two years. The fact that the decedent was a minor, or that the beneficiaries are minors, generally does not extend the deadline. As a result, statute of limitations defenses may be available in cases where suit is filed more than two years after the death.
Questions? Contact Steven Lucente with TLG Law at slucente@tlg-law.com or (704) 626-6552.
* This article is intended for general informational purposes only and does not constitute legal advice. Claims professionals should consult coverage counsel regarding the specific facts and applicable law in any particular claim.